Winning a house feels great.
Until you realize you might be agreeing to pay more than the home is worth.
That's the risk buyers take when they waive an appraisal contingency. In a competitive market like Wayne NJ, some buyers consider this strategy to make their offers more attractive to sellers. But there's a big difference between making a strong offer and taking on a financial risk you can't afford.
The question isn't whether waiving the appraisal can help you win. It's whether you can afford what happens if the numbers don't line up.
🚨 Thinking About Buying in Wayne NJ?
👉 DM "KPG" or call 201-400-7323
What Is an Appraisal Contingency?
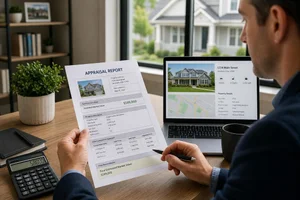
When you're financing a home, your lender will generally order an appraisal to help determine whether the property supports the purchase price. The lender uses that valuation as part of its lending decision.
An appraisal contingency gives a buyer contractual protection if the appraised value comes in below the agreed purchase price. Depending on the contract, the buyer may be able to renegotiate, seek another solution, or terminate the agreement under the contingency's terms.
Waiving that contingency means giving up some or all of that protection.
And no, it doesn't mean the lender stops caring about the home's value.
The lender can still require an appraisal and base the loan amount on its lending rules and the appraised value.
Why Would a Buyer Waive It?
Simple. Competition.
When multiple buyers want the same property, sellers compare more than the purchase price. They also consider the likelihood of a smooth closing and the risks attached to each offer.
An offer without an appraisal contingency may look more attractive because the buyer is agreeing to take on more of the valuation risk.
In Wayne and throughout Northern NJ, where buyers may compete for desirable homes, that flexibility can sometimes make a difference.
But there's a catch.
Making your offer stronger doesn't automatically make your financial position stronger.
The Real Risk Is the Appraisal Gap
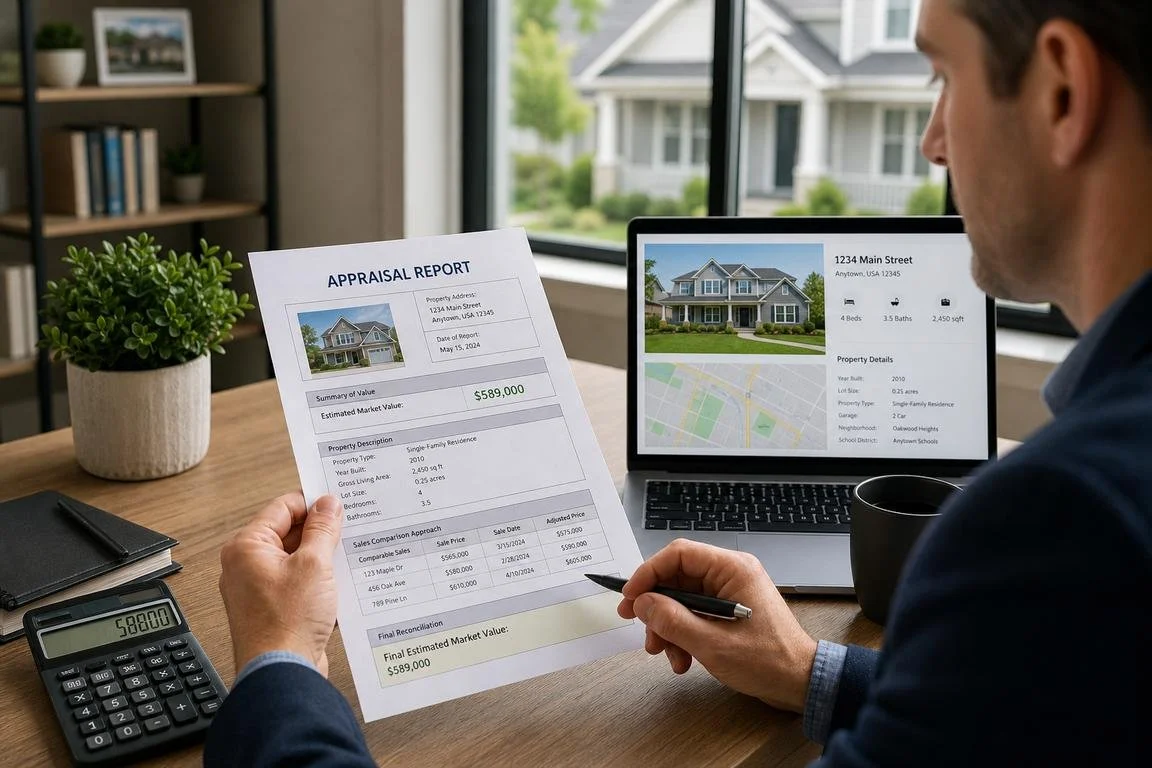
Let's say you agree to buy a home for $700,000, but the appraisal comes in at $675,000.
That's a $25,000 gap.
Your lender may calculate the loan using the lower appraised value, depending on the loan program and underwriting requirements. If that happens, you may need to bring additional cash to closing to cover the difference, renegotiate with the seller, or explore other options.
If you've waived the relevant contingency, you may have fewer contractual options if you can't make the numbers work.
And that $25,000 is on top of your down payment, closing costs, moving expenses, and whatever repairs the house needs after you get the keys.
This is where buyers get into trouble. They focus on winning the house without calculating what winning could actually cost.
When Waiving the Appraisal Might Make Sense
There are situations where accepting this risk may be reasonable.
You have substantial cash reserves. You can cover a potential appraisal gap without draining your emergency fund.
You understand the comparable sales. Recent, relevant sales support your offer price, even if the appraisal could differ.
You have a clear financial limit. You know exactly how much additional cash you could contribute.
The property fits your long-term plans. You're comfortable with the purchase even if the market value doesn't immediately match your offer.
Even then, waiving the contingency should be a deliberate decision made with your real estate agent, lender, and attorney—not a last-minute reaction to competing offers.
There's a Middle Ground
Waiving the appraisal contingency isn't always an all-or-nothing decision.
A buyer may consider an appraisal-gap clause that commits them to cover a specified shortfall up to a defined amount, subject to the contract's terms. For example, a buyer might agree to contribute up to $10,000 if the appraisal falls short.
That can make an offer more appealing while limiting the buyer's exposure compared with an unlimited commitment.
The details matter. Your lender and attorney should review the proposed language and how it affects your financing and contractual rights.
Final Thoughts
Waiving the appraisal contingency can help strengthen an offer, but it transfers risk to the buyer.
Before doing it, ask yourself one question.
If the appraisal comes in $20,000 or $30,000 below your offer, can you still comfortably close?
If the answer is no, reconsider the strategy. No house is worth putting your entire financial position at risk just to beat another buyer.
The goal isn't simply to get your offer accepted. It's to get to closing with a home you can afford and a financial plan that still makes sense afterward.
👉 DM "KPG" or call 201-400-7323